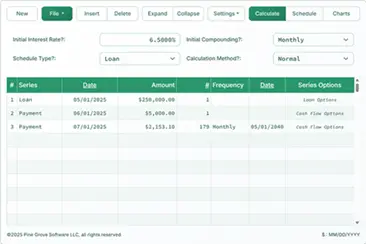
Accurate Amortization Calculator
Introduction to Amortization

Create a printable amortization schedule with dates to see how much principal and interest you’ll pay over time.
- Export to Excel/.xlsx and Word/.docx files.
- Calculate loan payment amount or other unknowns
- Supports 9 types of amortization.
- User can set loan closing date and first payment date independently.
- Automatically calculates prepaid interest
Create a printable amortization schedule that includes payment dates and annual subtotals. The schedule shows how much principal and interest you will pay over the life of the loan. The calculator can solve for any one unknown value: the payment amount, loan amount, interest rate, or loan term.
- What is an amortization schedule?
- An amortization schedule is a table that shows a loan’s complete repayment plan. It lists each payment and shows how much is applied to the loan’s principal and how much to interest, along with the remaining loan balance. Ideally, the schedule includes payment dates and year-end subtotals.
- How do I create an amortization schedule?
- Leave all inputs and settings at their default values. Then:
- Enter the Loan Amount.
- Enter the expected Number of Payments.
- Set the anticipated loan closing date and the first payment due date.
- Enter the expected Annual Interest Rate.
- Set the Payment Amount to 0.
(This tells the calculator to solve for the payment amount.) - Click either or .
- Leave all inputs and settings at their default values. Then:
These are the only steps required to generate your schedule.
If your loan terms differ from the calculator’s default settings, additional options are available.
Continue reading. The following sections explain each option in more detail. More…
Create an amortization schedule with user-specified dates.
To set your preferred currency and date format, click the “$ : MM/DD/YYYY” link in the lower-right corner of any calculator.
Information
Watch on YouTube
Watch on YouTube
Useful Details to Help You Get the Results You Need
First — You must enter a zero (0) in any field where you want the calculator to solve for a value.
Why is this necessary?
The calculator generates a schedule based on the loan terms you specify. The payment amount can be any value, as long as both the lender and borrower agree. There is no single “correct” payment. If the calculator always solved for the unknown value, this feature would not be possible.
TIP — Use the amortization schedule to verify the periodic interest charges. These interest amounts are the most important amounts for borrowers to review.
Four values you must always set:
- Loan Amount — The total amount borrowed, also called the principal. This value does not include interest.
- Number of Payments (term) — The length of the loan, measured in payment periods. This value depends on the Payment Frequency setting. For example, for a 15-year loan with biweekly payments, enter 390 as the number of payments.
(390 biweekly payments = 15 years) - Annual Interest Rate — The nominal (quoted) interest rate for the loan.
- Payment Amount — The amount due on each payment date. For a standard amortizing loan, this value includes both principal and interest.
Set one of the values above to 0 if you want the calculator to solve for it.
Which two dates are critical for an accurate amortization schedule?
If you only need an estimated schedule, you can skip this section.
For a schedule that is accurate to the cent — including correct calculation of stub period interest — it is worth taking a few moments to understand the available date settings.
- Loan Closing Date
- This is the date the loan funds become available. It is also called the origination date, loan date, or start date.
- First Payment Due
- This is the date the first payment is scheduled. For most loans, payments begin after the loan funds are received. For leases, this date may be the same as the loan closing date.
Important — Entering actual dates may result in interest and payment calculations that differ from those of other calculators.
This is by design.
However, if you want your results to match those from other calculators, set the “Loan Date” and “First Payment Due” so that the time between them equals one full period, based on the “Payment Frequency” setting.
Example: If the “Loan Closing Date” is April 10 and the “Payment Frequency” is “Monthly,” then set the “First Payment Due” to May 10 — if you want to estimate interest based on one full month.
More details about stub period options, including odd-day and irregular-period interest.
Four loan options you usually do not need to change
- Payment Period or Frequency — How often should payments be made? The calculator supports 11 options, including biweekly, monthly, and semiannual (commonly used for bond coupon schedules). Payment dates are calculated starting from the first payment due date, not the closing date.
- Compounding Period or Frequency — In most cases, the compounding frequency should match the payment frequency. This results in simple periodic interest. Selecting Exact/Simple calculates interest based on exact day counts using a simple interest method.
- Points — One point equals 1% of the loan amount. Points are commonly applied to U.S. mortgages.Learn more about points, fees, and APR support.
- Amortization Method — Leave this set to normal unless you have a specific reason to change it.See all nine amortization methods.
Five loan settings you may want to adjust

These options are available by clicking Settings.
- 360 / 365 / 366 — Days-per-year setting. Also called the day count convention, this affects interest calculations when you select a day-based compounding method (such as daily, exact/simple, or continuous), or when the loan includes an irregular first period. The 366-day option applies in leap years. Otherwise, 365 is used.
- Payment & Initial Period Interest Options — Controls how interest is calculated and displayed when the first period (from closing date to first payment) is longer or shorter than the standard interval.More details and examples.
- Last Period Rounding Options — Because payments and interest are rounded to the nearest cent (e.g., $345.0457 is rounded to $345.05), most loans require a rounding adjustment in the final period. A note on the schedule will show the exact adjustment.
- Points, Charges, & APR Options —Learn more about loan schedules with points, fees, and APR options.
- Year-End Month — Sets the month after which year-end and running totals are calculated. This is helpful for businesses with a fiscal year that does not match the calendar year.
FAQs — Frequently Asked Questions
- How do I calculate how much I can borrow?
- Set the Loan Amount to 0.
- Enter the Number of Payments.
- Enter the Annual Interest Rate.
- Enter the expected or target Payment Amount.
- Click or .
- How do I calculate how long it will take to pay off a loan?
- Enter the Loan Amount.
- Set the Number of Payments to 0.
- Enter the Annual Interest Rate.
- Enter the expected or target Payment Amount.
- Click or .
- What interest rate allows me to pay $500 per month?
- Enter the Loan Amount.
- Enter the Number of Payments.
- Set the Annual Interest Rate to 0.
- Enter $500 as the Payment Amount.
- Click or .
Printing the Payment Schedule
You can print from any type of device. For example, you can print a clear, well-formatted schedule directly from a smartphone to a wireless printer.(This printing functionality has been tested on several iPhone models printing to an HP LaserJet Pro.)
Do not use your browser’s built-in Print command.
Always print from the “Print Preview…” window. This screen includes a print button and export buttons for the .docx and .xlsx formats.
If you are using a modern browser, you can also print to a PDF.For example, in Chrome, open the browser menu (three vertical dots), choose Print…, then click Change… and select Save as PDF. Other browsers provide similar options.
If you encounter printing issues, please let us know which browser and version you are using. We test across several browsers, but we cannot test with all printer models.

(Chrome, Edge, and Firefox all offer a “Save to PDF” option in their print menus.)
How do I create amortization schedules in Excel (.xlsx) or Word (.docx)?
From the Print Preview screen (after the title page), you will see options to export the full amortization schedule as either an Excel (.xlsx) or Word (.docx) file. When you export to Excel, the schedule is saved as unformatted data. Dates and numbers are preserved as true Excel date and number values—not text—so you can apply your own formatting.
When you export to Word, the schedule is formatted for readability. You can edit the document, add notes, and customize fonts, styles, and layout as needed.The Word export is often more visually refined than the version printed directly by using the print button.
Amortization Equations
Payment Amount Equation
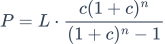
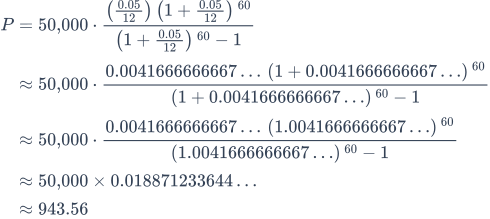
Fig. 4 — Step-by-step solution of the monthly payment amount equation.
Variables: L = 50,000; c = (5% ÷ 12 months); n = 60.
Variable Definitions
- P
- Payment amount
- L
- Loan amount
- n
- Number of months in the loan term.
- c
- Monthly interest rate (nominal annual rate divided by 12).
Calculation Steps
- Substitute the given values into the annuity payment formula:
P = 50,000 × ( (r/n)(1 + r/n)60 ) ÷ ( (1 + r/n)60 – 1 ), withr = 0.05andn = 12. - Evaluate the periodic rate:
r/n = 0.05/12 ≈ 0.0041666666667…and substitute it into the formula. - Simplify the base term:
(1 + 0.0041666666667…) ≈ 1.0041666666667…, keeping the exponent of 60 in both the numerator and denominator. - Compute the fraction:
(0.0041666666667… × (1.0041666666667…)60) ÷ ((1.0041666666667…)60 – 1) ≈ 0.018871233644…, then multiply by 50,000. - Round the payment to two decimal places for reporting:
P ≈ $943.56.
Step-by-step Solution – Fig. 4
P = 50,000 × ( (0.05/12)(1 + 0.05/12)60 ) ÷ ( (1 + 0.05/12)60 – 1 )≈ 50,000 × ( (0.0041666666667…)(1 + 0.0041666666667…)60 ) ÷ ( (1 + 0.0041666666667…)60 – 1 )≈ 50,000 × ( (0.0041666666667…)(1.0041666666667…)60 ) ÷ ( (1.0041666666667…)60 – 1 )≈ 50,000 × 0.018871233644…≈ 943.56
Final Answer
The final answer (P) is approximately 943.56.
Validate the calculator: Five-year (60-month) amortization.
| Loan Amount: | $50,000.00 | Number of Payments: | 60 |
|---|---|---|---|
| Annual Interest Rate: | 5.0000% | Payment Amount: | =943.56 |
| Loan Closing Date: | First Payment Due: | ||
| Payment Frequency: | Monthly | Compounding: | Monthly |
| Points: | 0.0 | Amortization Method: | Normal |
Notes:
- This example uses the same calculation shown in Fig. 4.
- Enter a zero for the payment amount. The calculated result matches the result above.
- The “Days In Year” setting has no effect in this example because the period spans exactly 60 months with no extra days.
Amortization Equation
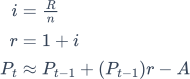
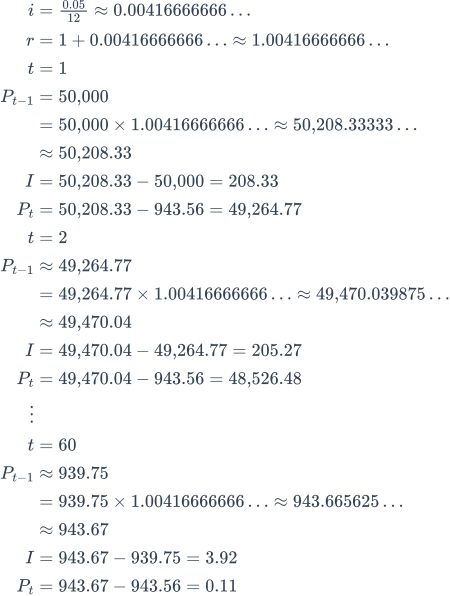
Fig. 6 — Step-by-step solution of the normal (general) amortization equation.
Variables: L = 50,000; R = 5%; n = 60; A = 943.56 (see Fig. 4).
Normal amortization for any period: ending balance = beginning balance + periodic interest − payment.
Variable Definitions
- R
- Nominal annual interest rate.
- i
- Periodic interest rate.
- I
- Periodic interest amount.
- r
- Growth factor per period (also called the per-period accumulation factor).
- t
- Period number.
- Pt-1
- Outstanding balance at the start of period t.
- Pt
- Outstanding balance at the end of period t.
- L
- Loan amount.
- n
- Number of months in the loan term.
- A
- Monthly payment amount.
Calculation Steps
- Compute the periodic rate:
i = 0.05/12 ≈ 0.00416666666…. - Compute the per-period growth factor:
r = 1 + i ≈ 1.00416666666…. - Set the period:
t = 1. - Start-of-period balance:
Pt−1 = 50,000. - Accumulate interest for the period:
50,000 × r ≈ 50,208.33333…. - Round the accumulated balance for display:
≈ 50,208.33. - Interest for the period:
I = 50,208.33 − 50,000 = 208.33. - Subtract the payment to get the end-of-period balance:
Pt = 50,208.33 − 943.56 = 49,264.77.
Step-by-step Solution – Fig. 6 (first period)
i = 0.05/12 ≈ 0.00416666666…r = 1 + i ≈ 1.00416666666…t = 1Pt−1 = 50,000= 50,000 × 1.00416666666… ≈ 50,208.33333…≈ 50,208.33I = 50,208.33 − 50,000 = 208.33Pt = 50,208.33 − 943.56 = 49,264.77
Validate the calculator: Five-year, 60-month amortization schedule.
| #/Year | Date | Payment | Interest | Principal | Balance |
|---|---|---|---|---|---|
| Loan start | 0.00 | 0.00 | 0.00 | 50,000.00 | |
| 1:1 | 943.56 | 208.33 | 735.23 | 49,264.77 | |
| 2:1 | 943.56 | 205.27 | 738.29 | 48,526.48 | |
| Periods 3–59: Intermediate calculations. | |||||
| 59:5 | 939.75 | ||||
| 60:5 | 943.56 | 3.92 | 939.64 | 0.11 | |
| Without any final rounding, a principal balance of $0.11 remains. | |||||
| 60:5 (final adjustment) | 943.67 | 3.92 | 939.75 | 0.00 | |
| Last payment increased by $0.11 due to interest rounding. | |||||
Notes:
- The results in the table above are taken from the calculator. They match the calculation shown in Fig. 6.
Beyond Basic Amortization Schedules
Need more options?
Explore seven additional loan amortization calculators.
- Mortgage Calculator — Estimate the future home value and compare it to the total mortgage cost.
- Extra Payment Calculator — Apply lump-sum or recurring extra payments with a full amortization schedule.
- Loan Calculator — Includes support for date-based calculations in a mobile-friendly layout.
- Auto Loan Calculator — Evaluate the full cost of vehicle ownership.
- Biweekly Calculator — Compare a biweekly schedule to a standard monthly repayment in a single view.
- Ultimate Financial Calculator — Build schedules with skipped payments, rate changes, and other advanced conditions.
- Loan Payoff Calculator — Track regular or irregular payments on any date.
This calculator is a comprehensive amortization tool. If you need help with a specific scenario or are not sure how to obtain a result, you can post a question in the comments section below.
Bill Phipps says:
By the way, I had never looked at the comments before, but this is a great tool and I happened upon it through pure luck and have used it ever since. Love the personalization that you can add to it and the features have really been extremely beneficial to me, a person who is not a whiz at computers. I genuinely appreciate the ability to use such a fine instrument and wanted to thank you for providing it.
Karl says:
You’re welcome. Now if only more folks would find it via either “pure luck” or users passing the word!
Aziz says:
karl,
This calculator works awesome! Small feedback.
When I change the data and click Calc button again it doesn’t calculate again based on changed data.
So I have to click clear and enter the data all over again to do the calculation again. So painful to keep reentering if i want to try different permutations and combinations for my loan.
Can you just not clear the amortization calcution table and retain the data in input fields?
Karl says:
Hi Aziz, what are you changing? For example, you can set up the first calculation to calculate the payment amount. If the calculator calculates 815.22 and creates a schedule, you should be able to change the payment to say 825.00 and click calc and a new schedule will be created using 825.00 as the payment.
Is this not happening for you?
Please give me a step-by-step example so I can try it and fix any issues.
Karl says:
But also, please realize this:
>>> When I change the data and click Calc button again it doesn’t calculate again based on changed data.
Taking my first example, if you change the interest rate and expect the calculator to recalculate the payment amount, that’s not how it’s supposed to work.
If you are changing any other loan attribute and you want to see the new payment, you must tell the calculator to calculate the payment by entering a 0 for payment.
This design feature is intentional so that users can use their payback details (like using a payment amount that is not the calculated payment result).
This is explained in a bit more detail on the page. Please see: “Always enter (and reenter) a 0 for the unknown value.” (or what you want calculated based on changed data.)
Chris Wheatley says:
When entering a short first period with Short Period setting of “Reduce all payments”, I’m seeing that the interest charged in the first period is reduced but the payments are not. The principal paid in the first period is increased in order to make the same payment, resulting in a lower payment and principal paid in the final installment.
Is there another setting I have to set to “Reduce all payments” for Short Periods?
I’m also seeing the same for Long Periods. Long Period setting is set to “Amortized” and I would expect all payments to be adjusted, I’m seeing that the interest is increased but the Principal is reduced to maintain the same payment as the standard period, resulting in a higher payment and principal paid in the final installment.
Am I misinterpreting what these settings are to accomplish?
Thank you for your time. Your calculator is great!
Karl says:
Please provide all the loan details so that I can take a look to see the actual results you are getting. Thanks.