
The Mortgage Center @ AccurateCalculators.com
Introduction
Obtaining a mortgage can be stressful, even when the process is straightforward. The Mortgage Center @ Financial-Calculators.com provides background information to help you with each step in the process.
According to The FRED® Blog — Comparing household assets across the wealth distribution (April 4, 2024), a home is one of the most commonly held household assets, and home equity is a major contributor to household wealth:
As of fourth quarter 2023, households in the bottom 50% hold just over 50% of their assets in real estate. Households in the top 1% and top 0.1% hold 13.1% and 9% of their total assets in real estate, respectively.
If you are undecided about buying a home, the information below may help you make an informed decision.
This guide covers the following topics:
- The key factor in comparing mortgages — the annual percentage rate (APR)
- The potential tax benefits of having a mortgage
- Is buying a house a good investment?
- How making extra payments can save you money
- Two practical tips for saving money
- Understanding adjustable-rate mortgages (ARMs)
- Your comments and questions
What Is a Mortgage?
A mortgage is a loan secured by real estate.
What does this mean in practice?
In general, lending falls into two categories:
- A lender may provide funds based on your creditworthiness (or for personal reasons, such as trust or a relationship). For example, credit card issuers extend credit based on repayment history. If you fail to repay, the lender cannot seize your property. This type of borrowing is called an unsecured loan.
- The second category includes loans backed by specific assets. If the borrower fails to repay as agreed, the lender has the legal right to take possession of the pledged asset(s). This is known as a secured loan. A mortgage is a secured loan because the lender may claim ownership of the property if the borrower defaults.
The Annual Percentage Rate — APR
Use the APR to compare mortgage offers.
In the U.S., the APR is one of the few lending figures regulated by the federal government under the Truth in Lending Act (TILA). Some people assume that the government regulates payment amounts. It does not. A lender may generally offer any payment amount, provided the borrower agrees to the terms.
However, the APR is different from the payment amount. The APR is not simply an interest rate. It is a rate of return on the loan, and theTILAexplicitly defines how it must be calculated. (The Act does not set minimum or maximum APR values.) The Consumer Financial Protection Bureau, which assumed this responsibility from the U.S. Federal Reserve, oversees compliance.
The APR benefits borrowers. Since TILA was enacted in 1968 and a standardized method for calculating APR was mandated, consumers have been able to compare loan offers more consistently. Before this disclosure requirement, borrowers often compared only interest rates or payment amounts and then tried to include fees on their own.
For example, was a 5% mortgage interest rate with $2,000 in closing costs a better choice than a 5.125% mortgage with lower closing costs?
There was no clear answer without performing manual calculations, and borrowers risked choosing the more expensive loan.
Today, lenders are required to comply with TILA. This means they must calculate the APR using the same federally mandated method. (The Act itself is lengthy.)
Although the APR is useful, it has a limitation: The APR is a “personal number” because fees, timing, and loan details differ from borrower to borrower. Borrowers cannot reliably compare lenders based only on advertised APRs. These figures are reference points only.

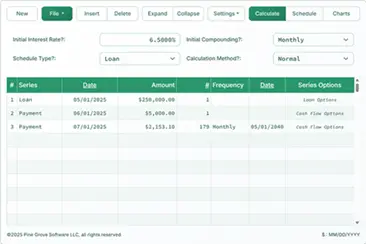
(Images are from the Accurate Mortgage Calculator.)
Several factors influence your personal APR, including the quoted payment amount, fees, and other charges. Required inspection reports, attorney’s fees, and loan application fees are also included in the APR calculation. Because these costs vary by lender, your APR will vary as well.
Because advertised APRs alone are not sufficient for accurate comparisons, you should request an APR Disclosure Statement from each lender. Alternatively, use a calculator that performs an APR calculation based on your specific loan terms.
How do you calculate an APR?
The Accurate Mortgage Calculator calculates the APR for you. To ensure accuracy, provide the following information:
- Loan amount
- Payment amount (either the lender’s quoted amount or the calculated amount)
- Other loan details: amount, term, and interest rate
- Points, if applicable
- Total of all required lender fees and charges
- PMI rate, if applicable
(Optional charges that the lender does not require—for example, an upgraded septic inspection—are excluded from the APR calculation.)

There is an additional important consideration when comparing APRs: The lowest APR is not always the best option.
Why might a borrower choose a loan with a higher APR?
As noted above, the APR is a “personal number.” For example, a 30-year loan’s APR assumes that you will keep the loan for the full 30-year term. The same principle applies to a 15-year mortgage or any other term.
Your plans may be different. If you intend to sell the property before the end of the term, the calculated APR will not reflect your true cost. Fees and charges are usually paid at closing, so when the loan is repaid early, those fees have a proportionally greater effect on your effective APR.
In general, the shorter the time you hold the loan, the greater the impact of fees—which increases your effective APR. For example, paying points to lower your rate may appear to reduce APR compared with another offer, but that benefit may apply only if you keep the loan for the full term. If you expect to sell sooner, a loan with a slightly higher AP