U.S. National Debt Calculator
Introduction to the National Debt Calculator

The U.S. National Debt Calculator allows you to accurately amortize any debt up to 99 trillion dollars!
- Supports both “Normal” and Interest-Only loans.
- Create a bond coupon schedule.
Did you arrive on this page expecting a strong argument against the U.S. National Debt?
If so, you may be disappointed.
As a U.S. citizen, I am concerned about the debt, and I will address that concern shortly. I will also raise a question that few people appear to ask—not elected officials, not the media, and not voters. If that discussion is what you want to read, skip the next section and continue below the calculator.
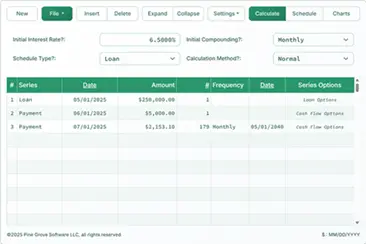
If you continue, I first want to explain how this calculator works because it operates differently from many amortization schedules. I created it for two purposes. First, I wanted a calculator that could handle very large debt amounts. And what debt is larger than the current National Debt of the United States? There is no larger debt.
The Calculator-Calculate your share of the U.S. national debt.
To set your preferred currency and date format, click the “$ : MM/DD/YYYY” link in the lower-right corner of any calculator.
Information
Our National Debt and the Sources Used
At times, large municipalities or other government entities have issued debt in excess of one billion dollars and needed a coupon payment schedule. This calculator creates an amortization schedule for bond debt. When you preview or print the schedule, there is no mention of “National Debt.” The printed schedule matches the style of other schedules on this site. This is intentional.
Second, this calculator introduces the concept of shared debt. For example, a parent and child may agree to split payments on a student loan. This calculator supports that situation. Enter the total loan amount and enter two for the number of households. The calculator divides the payment in half, and the schedule amortizes half the debt.
All values reflect the latest available data as of March 2024. (Links open in a new tab.)
According to the U.S. Treasury Department, the debt is nearly $34.5 trillion. The exact amount is preloaded, and clicking the Clear button resets the value.
The debt increases daily. If you want to update the value, use the TreasuryDirect link titled “Debt to the Penny.”
The U.S. Census Bureau publishes the number of U.S. households. The most recent figure (131,434 in thousands) is from November 2023. To check for updates, see: Table HH-1. Households by Type: 1940 to Present (.xls file).
The default interest rate is the current coupon rate on the 30-year U.S. Government Bond, as reported by Bloomberg (as of March 2024, 4.25%). This rate is used to model a 30-year amortization.
In one sense, this slightly overstates the problem. Much of the debt has maturities shorter than 30 years, and many securities carry rates below 4.25%. For example, 10-year bonds currently have a 4.0% coupon rate. Even a 0.25% difference can produce a significant change in interest costs on debt exceeding $34 trillion. (Rates have recently fluctuated more than usual, so this information may become outdated quickly. The links are provided for verification.)
On the other hand, using 4.25% may understate the problem. If the Government borrows for five years, future interest rates are unknown. The debt may need to be refinanced at a rate higher than 4.25%.
In any case, 4.25% is a reasonable assumption. You may change the rate as needed.
Why does the debt have to be refinanced?
About Bonds and Refinancing
Government debt is financed with bonds (and short-term Treasury notes). Governments sell bonds to raise funds. Bondholders receive coupon payments, usually paid every six months.
Coupon payments are interest payments only. They do not reduce the principal.
Therefore, the borrowing functions like an interest-only loan. The principal balance does not decline.
You can model this by setting the amortization method to interest-only. A single large payment is due at maturity. If the principal is not available, the debt is refinanced when the bond matures.